Blog / Jacksonville Mazda Dealer

Introducing the 2024 Mazda CX-90 PHEV

image

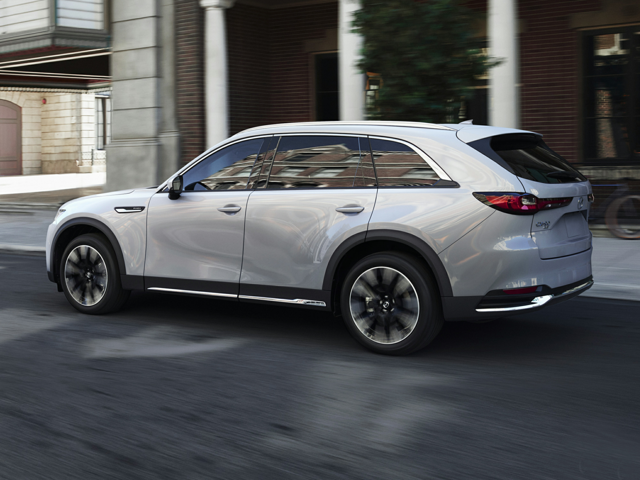
Now at your local Mazda dealer, the CX-90 is a new full-size crossover SUV that offers tons of high-end features and a spacious three-row cabin for a great price. One of its variants is a plug-in hybrid promising extended range and the ability to operate the vehicle solely on electric power. Meet the 2024 Mazda CX-90 PHEV!

From Your Mazda Dealer: Introducing the 2024 Mazda CX-90 PHEV

Powertrain

Combining a 68-kW electric motor and a 2.5L e-Skyactiv PHEV inline-4, the CX-90 PHEV's powerplant produces a hefty total of 323 horsepower and 369 lb-ft of torque. An 8-speed PHEV e-Skyactiv automatic transmission ensures plenty of grunt at all revs and features a manual shifting mode with steering wheel-mounted paddle shifters that will impress any enthusiast. The standard i-Activ all-wheel drive system is rear-biased for a sportier driving experience.

An EPA-rated driving range of 490 miles and a fuel economy of 56 MPGe combined comes thanks to the CX-90's 17.8-kWh lithium-ion battery, which also allows for an all-electric driving range of up to 26 miles. With a Level 1 (120-volt) charger, the battery can be charged from 20% to 80% in under seven hours. An available Level 2 (240-volt) charger will do the job in just 90 minutes.

Chassis

The CX-90 features a fully independent suspension consisting of a double-wishbone front suspension and a multi-link rear suspension. While this setup has been tuned to provide sharp and nimble handling, the ride remains exceptionally smooth even when traveling over bumpy roads. Precise power steering comes with variable assist, making it easier to maneuver the vehicle at any speed.

Powerful 13.7 vented disc brakes and 13.8-inch solid disc brakes bring the CX-90 to a quick stop.

Cabin

As you can expect from a Mazda, the CX-90 houses a sleek, elegant interior that boasts ample use of premium materials. Beautiful metallic accenting and wood trim can be found throughout the cabin, and the supportive seats are wrapped in genuine leather upholstery. Tri-zone automatic climate control, three-level heated seats, and an 8-way power driver's seat with lumbar support are all standard on the Preferred model.

Up to eight passengers may be seated within the CX-90's three rows, but buyers can opt for a seven-seat configuration that replaces the reclining second-row bench seats with two captain's chairs. Either way, the seats quickly and easily slide and tilt forward to provide access to the third row.

Multimedia and Connectivity

The feature-packed Mazda Connect infotainment system is accessed through a 10.25- or 12.3-inch display and the intuitive Commander control knob. This system includes Apple CarPlay/Android Auto smartphone integration, Bluetooth hands-free technology, and HD radio. Dual USB ports can be found in every row, plus Premium and Premium Plus models offer a wireless phone charger and a 12-speaker Bose Centerpoint surround sound system.

With its super-efficient powerplant and a wealth of comforts, the CX-90 is a compelling choice for any family. Get in touch with Tom Bush Mazda in Jacksonville, FL today and schedule a test drive with this exciting model!
Posted in:

Related Posts

Bad Credit Car Loans in Jacksonville Preparation Guide

Bad Credit Car Loans in Jacksonville Preparation Guide

Bad credit car loans can feel harder to approach when you do not know what to prepare first. In Jacksonville, a better starting point is getting your financial details organized before you begin an application. That means reviewing your credit, understanding your budget, and knowing what information a lender may review. Preparation does not promise a loan result. However, it gives you a clearer view of the numbers and questions that may come next. Start With Your Credit and Current Budget Before you apply, review your credit reports and your current monthly obligations. Additionally, look for incorrect balances, unfamiliar accounts, or outdated information. If something looks wrong, research the issue before moving deeper into the financing process. Additionally, write down your regular monthly expenses. Include housing, insurance, utilities, current loan payments, and other recurring obligations. Moreover, compare those costs with the payment range you could manage each month. Still, the monthly payment should not stand alone. A longer loan term can reduce the payment while increasing the total amount paid. Therefore, start with the full budget instead of choosing a vehicle from payment alone. For bad credit car loans, your credit report and budget also give you useful questions for the finance team. You can ask what information the application needs and what loan terms require closer review. That preparation keeps the discussion focused on numbers you understand. Tom Bush Mazda also has a dedicated bad and low credit assistance page where Jacksonville shoppers can review dealership financing resources before applying. What Should You Prepare Before Applying for a Car Loan? You should prepare identity, income, housing, and current financial information before starting an application. However, exact document requests can vary by lender. The goal is to have accurate records ready if they are requested. A few categories are worth organizing before you begin: Bring current identification and address information so application details are accurate from the start. Gather recent income records in case the lender asks for documentation supporting current earnings. Keep current debt and payment information nearby so you can answer financial questions accurately. If you already know which vehicle you want, keep its basic details handy. However, do not assume the financing terms are final because you selected a vehicle. Therefore, the application review and final contract establish the actual loan terms. It also helps to organize trade information before visiting the dealership. Bring the current loan payoff amount if you still owe money on the vehicle. Additionally, note the vehicle identification number, mileage, and general condition. For bad credit car loans, this preparation gives you cleaner information to work from. It also reduces the chance that an important number gets overlooked during the financing discussion. If you are ready to provide your information, you can also move directly to the Tom Bush Mazda finance application. Plan Your Down Payment and Trade Before Choosing a Vehicle With bad credit car loans, a down payment reduces the amount you need to finance. Cash can serve that purpose, and positive trade equity can also contribute. Therefore, it helps to know what you can put toward the purchase before comparing loan structures. Your trade deserves its own review. Additionally, start by estimating its current value and checking the exact payoff amount. The difference between those numbers tells you whether you have positive or negative equity. Before you discuss a trade, write down three figures: Record the estimated trade value so you have a starting point for the vehicle. Record the exact payoff amount if money is still owed on the current loan. Record your planned cash down payment so you can see the full upfront amount. Positive equity means the trade value exceeds the payoff amount. That value can reduce the remaining purchase amount. By contrast, negative equity means the payoff exceeds the trade value. If negative equity exists, ask how it will be handled in the new transaction. Some deals may include that remaining balance in the new financing amount. As a result, the amount financed can rise even when the replacement vehicle costs less than expected. Moreover, these figures make it easier to compare early estimates with final numbers. They also give you clearer questions for the finance team. Shoppers who want to compare vehicle options before discussing final terms can review current Mazda inventory at Tom Bush Mazda. Understand Co Signers and Prequalification Before Applying With bad credit car loans, a co signer agrees to share legal responsibility for the loan. If the primary borrower does not pay, the co signer can become responsible for repayment. Therefore, both people should understand the obligation before signing anything. A co signer should never be treated as a casual addition to an application. Missed payments can create financial problems for both people. Consequently, discuss repayment plans before submitting a joint application. Prequalification can also appear during early financing research. It can provide preliminary information based on the details supplied during the process. However, preliminary terms are not the same as a final loan contract. Final terms can change after a lender completes its review. For this reason, use prequalification as an early reference point, not a final answer. Compare any later offer with the information you received earlier. When reviewing either stage, focus on the full loan structure. Look at the amount financed, annual percentage rate, loan term, and estimated payment together. That gives you a more complete view than a payment figure alone. For a dealership specific next step, the Tom Bush Mazda finance center can help connect your application with the dealership’s available financing process. What Should You Review Before Signing an Auto Loan? Before signing bad credit car loans, review the amount financed, annual percentage rate, loan term, payment, and total amount paid. These figures show how the loan is structured. Before you sign, confirm each of these items: Confirm the amount financed matches the agreed purchase details and any approved additions. Review the annual percentage rate and loan term together instead of focusing only on the monthly payment. Check trade payoff details carefully if your current vehicle is part of the transaction. Therefore, first confirm the amount financed. Make sure it reflects the agreed vehicle price, down payment, trade details, and any approved additions. If a number looks different, ask for an explanation before signing. Next, review the annual percentage rate and loan term. A lower monthly payment may come from a longer term. Therefore, compare the total cost across the full contract. Also, check that your trade payoff appears correctly if a trade is part of the deal. If negative equity is included, confirm where that balance appears. Knowing that figure matters before you accept the contract. Finally, review every page before you sign. Ask questions about anything that is unclear. A finance agreement should make sense to you before you commit to it. Bad credit car loans become easier to review when your financial information is organized. Tom Bush Mazda in Jacksonville has a credit assistance resource for customers who want to explore financing options. From there, you can continue to the finance application when you are ready to provide your information.

Mazda CX 90 vs Honda Pilot Space Comfort and Driving Feel

Mazda CX 90 vs Honda Pilot Space Comfort and Driving Feel

Mazda CX 90 shoppers looking at three-row SUVs usually need more than a seating count. Because families use three rows differently, passenger room, cargo space, and road feel all deserve attention. The Honda Pilot approaches those needs with a roomy cabin and flexible seating. By contrast, the Mazda CX-90 takes a different path with standard all-wheel drive and a turbocharged inline-six. Looking at both layouts side by side makes the differences easier to judge. Mazda CX-90 and Honda Pilot Take Different Approaches to Three-Row Travel Both SUVs offer three rows and seating for up to eight in selected configurations. However, their proportions tell different stories. The CX-90 rides on a 122.8-inch wheelbase. The Pilot uses a 113.8-inch wheelbase. Therefore, a longer wheelbase does not guarantee more cabin room. Seat placement and cabin packaging also shape usable space. Mazda gives the CX-90 a long hood and a drivetrain layout that supports its road-focused character. Honda uses its cabin space differently. The Pilot puts strong emphasis on passenger room and cargo volume. Consequently, those choices become clear when you move past exterior size and inspect each seating row. For a family, the useful question is simple. With that in mind, where will people sit most days? A household using the third row every week may judge these SUVs differently. Another family may fold those seats for cargo. In addition, steering feel and power delivery deserve attention during the same evaluation. Jacksonville shoppers can also review Tom Bush Mazda’s current Mazda inventory to see which CX-90 configurations are currently available. How Different Is the Third Row in the Mazda CX-90 and Honda Pilot? The third rows differ most clearly in measured legroom and shoulder room. The 2026 Pilot lists 32.5 inches of third-row legroom. Published CX-90 specifications list 30.4 inches. Therefore, that gap deserves attention when older children or adults use the rear seats. Moreover, seat count needs context. Both SUVs can seat up to eight, but trim choice changes the second-row layout. Some versions use captain's chairs, while others use a bench. As a result, that choice changes passenger flow, center access, and access to the third row. Beyond that, check more than legroom during a visit. Sit in every row that your household plans to use. Move the second row into a position that gives both rows enough knee room. Afterward, check headroom, shoulder room, foot space, and entry clearance. In addition, families with child seats should test their normal arrangement. A third row may look spacious when the second row is empty. However, the same layout can feel different once child seats, bags, and daily gear are in place. Cargo Space Depends on Who Is Coming Along Therefore, cargo numbers become useful only when they match the seating layout you plan to use. The Pilot provides more cargo volume in published measurements. Honda lists 18.6 cubic feet behind the third row before its maximum measurement method is applied. Published CX-90 specifications list 14.9 cubic feet with all seats in place. Still, the bigger question is how much space remains while passengers stay seated. A family carrying six or seven people cannot use the same cargo figure as someone who folds both rear rows. For this reason, space behind the third row deserves close attention for school trips, airport runs, or weekend travel. When comparing both SUVs, bring a mental list of what usually rides with you: Check whether your stroller, sports bag, or cooler fits with the third row raised. Fold only the seats you would normally fold on a normal trip, then inspect the remaining floor area. Look at the cargo opening, floor height, and seat-folding process, since shape can matter as much as total volume. Additionally, a tape measure can be useful if you carry an item with fixed dimensions. Cubic feet describe total volume. However, they do not tell you whether a wide or tall object will fit through the opening. The Powertrains Explain Much of the Difference From the Driver's Seat By contrast, the CX-90 and Pilot take different mechanical approaches. Mazda uses a turbocharged 3.3-liter inline-six with an eight-speed automatic. The standard CX-90 3.3 Turbo produces up to 280 horsepower and 332 pound-feet of torque. Mazda also includes i-Activ all-wheel drive across the CX-90 lineup. Honda uses a naturally aspirated 3.5-liter V6 with a ten-speed automatic. The 2026 Pilot produces 285 horsepower and 262 pound-feet of torque. Front-wheel drive is offered on selected trims, while Honda's i-VTM4 all-wheel drive is available or standard elsewhere in the lineup. However, horsepower alone does not explain how each SUV responds. Torque output and engine speed matter during acceleration. The Mazda's standard turbo engine reaches its 332 pound-feet at 2,000 rpm. The Pilot reaches 262 pound-feet at 5,000 rpm. As a result, the two engines deliver power differently. Therefore, the road test should focus on what you feel through normal inputs. Accelerate from a stop. Merge onto a faster road. Make a smooth turn at neighborhood speed. Notice steering weight, throttle response, transmission shifts, brake feel, and body motion. Moreover, Mazda's brand philosophy places strong emphasis on connection between the driver and the car. The CX-90 carries that idea into a larger three-row format. By contrast, Honda gives the Pilot a different focus. Cabin room and flexible family seating take a larger role in the package. Jacksonville shoppers who want to compare available configurations can browse Tom Bush Mazda inventory before planning a visit. What Should You Compare During a Three-Row SUV Test Drive? For this reason, a useful test drive checks the parts of the SUV your household will use every week. Start with seating, then cargo, then the drive itself. Consequently, that order keeps the evaluation tied to your daily routine. Before leaving the lot, set the driver's seat where you want it. Then check the second and third rows without moving that front position. Test seat access and cargo space with the cabin arranged for your normal passenger count. Afterward, use familiar driving inputs on the road. Try a stoplight launch, a steady cruise, a lane change, and a low-speed turn. Listen for cabin noise and pay attention to how quickly each drivetrain responds. A strong comparison also includes a few practical checks: Sit in every row your household expects to use on a regular basis. Load the type of gear you normally carry and check the remaining cargo area. Compare steering, throttle response, braking, and ride quality on similar roads. In the end, the Mazda CX-90 and Honda Pilot solve the same three-row task in different ways. The Pilot gives more published space in several cabin and cargo measurements. The CX-90 pairs three-row seating with a turbo inline-six and standard all-wheel drive. Your strongest comparison comes from testing both with the same people, gear, and route you expect to use after purchase. When you are ready to look more closely at the Mazda side of the comparison, you can explore current Mazda vehicles at Tom Bush Mazda.

First Time Car Buyer Guide Jacksonville Finance Prep

A first time car buyer guide for Jacksonville should begin with a budget, documents, insurance details, and clear financing questions. Preparation does not promise approval or a certain offer. However, it gives a lender the records needed to review the application. Start by setting a total vehicle range before choosing a Mazda. Include the price, taxes, registration, insurance, fuel, and future service. Therefore, the monthly payment should not stand alone. A longer loan term can lower the payment while raising the total paid. In addition, a larger upfront amount can reduce the amount financed. These choices should fit your full household budget. Can a First Time Shopper Finance a Mazda With No Credit? No credit and poor credit are not the same. No credit means a lender has little recorded borrowing history to review. Poor credit reflects recorded issues within an existing file. Financing may still be possible with limited history. However, each lender uses its own review process. Income, employment, residence, debt, and available records may all enter that review. A lender may also examine how long you have lived or worked in one place. Therefore, stable records can give the application more context. They do not guarantee approval. First time shoppers should check their credit reports before applying. This step can reveal errors, old addresses, or unfamiliar accounts. In addition, it helps explain what a lender may see. Do not confuse limited history with negative history. This guide focuses on limited or no history. Recorded late payments, collections, or defaults require a separate finance discussion. Documents to Prepare Before Applying A complete file can reduce delays during the finance review. Which documents may be requested? Common records confirm identity, income, residence, employment, and insurance. Prepare these items before visiting: Bring a current government issued photo ID that matches the application name. Bring recent pay statements or other accepted income records requested by the lender. Bring proof of residence, such as a current utility bill or lease document. Bring insurance information or contact details for the provider you plan to use. Bring employer details, including its name, address, phone number, and your start date. Bring trade documents when another vehicle may enter the transaction. A lender may request other records after reviewing the application. Therefore, ask which documents apply before your appointment. Current program rules can also change. Make sure each record uses the same legal name and current address. Inconsistent details can slow the review. Furthermore, keep digital copies available in case another document is requested. Should a First Time Shopper Use a Cosigner? A cosigner joins the credit obligation and accepts legal responsibility for repayment. Should every first time shopper use one? No. The decision should follow a clear discussion about payment duty and credit risk. A lender may review the cosigner’s income, debt, and credit file. However, a cosigner does not remove the primary borrower’s duty. Both people can face credit harm after missed payments. Before asking someone to cosign, discuss the payment date, account access, and response plan for a missed payment. In addition, decide how both people will track the loan. Down payment planning belongs in the same discussion. Money paid upfront lowers the amount financed. A trade may also reduce that amount after value and payoff review. Use these questions before choosing an upfront amount: How much money will remain for insurance, registration, fuel, and early service? Will a larger upfront amount reduce the monthly payment enough for the budget? Does a trade have an existing payoff that must be cleared first? Will the lender or current program require a minimum upfront amount? Do not empty emergency savings only to lower the loan balance. Therefore, keep a reserve for costs that arrive after delivery. Prequalification and Finance Application Steps Prequalification gives an early estimate from the information supplied. It does not equal final approval. A full application requires deeper lender review and the selected Mazda details. Some prequalification tools may use a soft credit inquiry. Others may use a hard inquiry. Therefore, read the disclosure before submitting personal information. After prequalification, compare the estimated range with your vehicle budget. Then, choose a Mazda that fits the planned price range. The exact price, taxes, fees, and trade details will shape the final request. The full application may ask for identity, income, residence, employment, and credit information. In addition, the lender may request more documents before making a decision. Final terms can differ from an early estimate. Therefore, compare the written offer with the amount you planned. Do not rely on a verbal summary alone. What to Confirm Before Choosing a Mazda Before signing, review every number in the final agreement. Which figures matter most? Confirm the vehicle price, upfront amount, trade credit, financed amount, APR, term, payment, fees, and total payments. A lower payment may come from a longer term. Therefore, compare the total paid across the full loan. Also, confirm whether optional products appear in the financed amount. Review these final points: Confirm that the vehicle price matches the agreed figure. Confirm that the trade value and payoff appear correctly. Confirm the APR, loan term, monthly payment, and first payment date. Confirm every fee and optional product before signing. Confirm that the final paperwork matches the Mazda you selected. Keep copies of every signed document. Tom Bush Mazda maintains a first time owner page with current program details. Jacksonville shoppers can review that page before applying. In addition, the finance page and payment calculator can support early planning. A first time car buyer guide should lead to informed questions, not promises. Prepare the records, compare the full loan, and review every term. Then, choose the Mazda and finance path that fit your budget.